What is a banking pool, and how does it affect you?
1. Banking pool: What it is, what it's used for, and who can ask you for it
Do you know what a banking pool is?
It’s one of those financial terms that might throw you off if you’ve never heard of it.
It’s in your best interest to understand it, since whether or not you can secure certain types of financing or financial assistance may depend on it.
Below, we’ll explain it in detail. We’ll also take this opportunity to explain what CIRBE is—the other credit report you should be familiar with.
2. What Is a Banking Pool?
A banking pool is a detailed banking risk report. In other words, it includes a thorough analysis of all the sources of financing available to a legal entity over a specific period of time.
In general, the banking pool is an evaluative compilation of the following elements:
– Loans.
– Lines of credit.
– Mortgages.
– Financing transactions.
– Guarantees.
– Discount lines.
– Leasing lines.
– Confirming lines.
– Factoring lines.
– Other financing instruments.
3. What is the purpose of a banking pool?
A banking pool serves two fundamental purposes:
– Internal use: It helps ensure proper management of banking risk and provides insight into the company’s actual financing costs.
– External use: It provides valuable information when seeking new financing opportunities. The reason is simple: banks will find it easier to evaluate you and decide whether to grant you additional financing. Typically, banks cross-check this report with the CIRBE.
4. What will banks ask you for when you want more financing?
As we’ve already mentioned, you’ll need to have an up-to-date banking pool whenever you want to work with a new financial product or service through a credit institution.
At the same time, you’ll need to submit it in addition to the usual information:
– Accounting information: Income statement and balance sheet.
– Tax information. Most recent tax returns filed: personal income tax, corporate income tax, VAT…
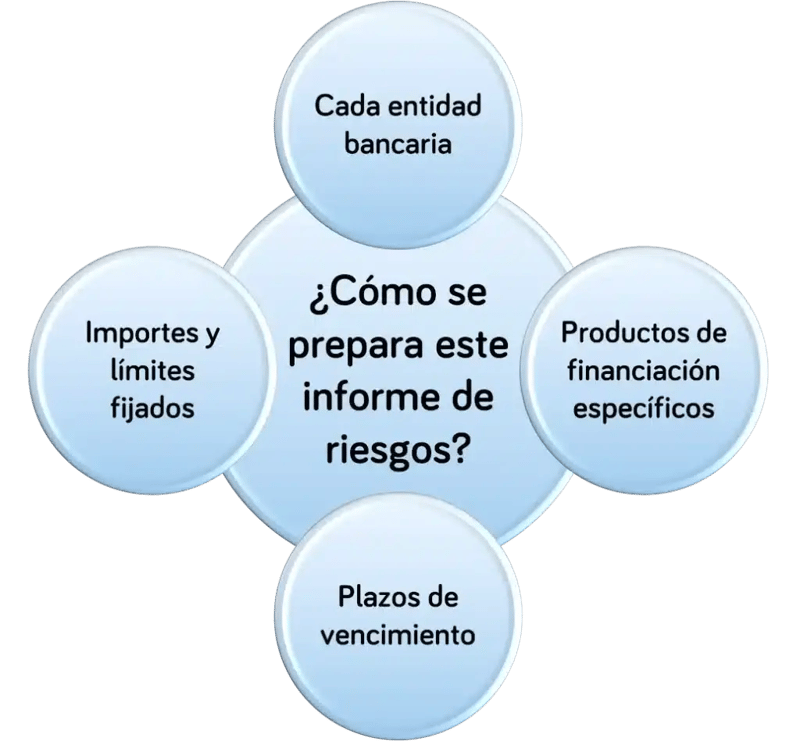
5. How do you prepare this risk report?
Once you understand what a banking pool is and its purpose, it’s easy to imagine what information it contains.
In summary, you must include:
– The name of each bank you are working with as of that date.
– The names of the specific active financing products.
– The maturity dates for each of these financial products.
– The amounts and limits set for each of them.
It’s also often helpful to support this information with supporting documentation. In this regard, a good option is to include recent statements for each of these products, account ownership certificates, or the underlying contracts. Another alternative is to provide a statement of your outstanding debts with each of the banks.
This way, you provide reliable and easily verifiable documentation. If you aim to convince the recipient of your financial reliability, this risk report will help. Transparency and clarity are highly valued in these situations.
6. CIRBE, the Other Major Risk Report
The Bank of Spain’s Risk Information Center—also known as CIRBE—is tasked with compiling risk reports on all companies in the country.
Does that seem strange to you?
It shouldn’t, since this happens every time a bank is evaluating whether to grant you some type of significant financial transaction.
CIRBE is a public database—though confidential in nature (not accessible to just anyone)—that compiles all the risk data on credit institutions’ clients.
Each financial institution provides its information, which allows others to access the actual data and assess the risk associated with their decisions.
Are the pool and the CIRBE exactly the same?
They’re similar, yes, but not identical.
Financial institutions, for example, are not required to report loans under 6,000 euros. In other words, if you have a 10,000-euro loan, it will appear in the CIRBE, but it won’t if you have two 5,000-euro loans.
However, this information is included in the pool.
Additionally, some forms of alternative financing do not necessarily appear either, such as promissory note discounting and invoice advances.
7. Who can request a credit pool report?
As a general rule, financial institutions are the ones that request this documentation from their potential customers. They use it as a supplement to the CIRBE to decide whether or not to approve your loan application.
In addition, on occasion, some investors may ask you for this information. It is undoubtedly very useful for providing a detailed snapshot of your current financial situation.
Likewise, on some occasions, it is compiled internally within the company. For example, the CFO or another executive may find it useful to gather this information to inform decision-making.
At this point, you’re in a position to deal with your banking network with much greater rigor and discernment. When someone requests this information, you’ll have a clear understanding of why they’re asking and whether or not you should prepare it.
8. How can we at WorkCapital help you?
Generally, banks have many requirements, and it’s very likely they won’t want to finance you—or won’t want to do so to the extent you need—due to your risk profile, which means your liquidity problems won’t be resolved.
Therefore, in that situation, we recommend turning to alternative financing.
At WorkCapital, we offer alternative financing products that do not appear in these types of reports.
Feel free to contact us with no obligation—we’d be happy to help you.