How can you prove your financial stability?
1. What is financial solvency?
Financial solvency is a fundamental term in the financial world, as it refers to the ability of a person or entity to meet their financial obligations. This ability reflects an economic agent’s financial health, and its importance extends to various areas, such as access to credit, economic stability, and financial reputation.
Financial Solvency and Its Context
In a financial context, financial solvency indicates a favorable position in which assets exceed liabilities. This positive status allows businesses and individuals to access better credit terms—including the best credit cards with benefits tailored to their financial profile, as seen at —and to avoid situations of insolvency.
Factors Influencing Solvency
An entity’s creditworthiness can be influenced by several factors. Internally, expense control and debt management are critical. Externally, the global economy and tax regulations also play a significant role in maintaining or altering the level of creditworthiness.
The Importance of Maintaining Good Creditworthiness
Maintaining good financial solvency is crucial. It not only allows access to financing on favorable terms but also ensures operational continuity and minimizes financial risks. For individuals, it provides financial security against unforeseen events.
Solvency vs. Liquidity
It is vital to differentiate between solvency and liquidity. While solvency focuses on the long-term ability to meet obligations, liquidity centers on the immediate ability to convert assets into cash.
2. Solvency Statement: Key to Financial Stability
The solvency document not only certifies an entity’s ability to pay but also acts as a shield for building relationships of trust across multiple economic sectors.
Impact on Financial Sectors
Solvency certificates have become an essential tool in sectors such as real estate, where they guarantee tenants’ ability to meet their obligations. This guarantee extends to other areas, such as public bidding, where transparency and financial security are crucial.
Future Innovations
In the near future, the digitization of solvency documents could make them more accessible and efficient, making it easier to obtain them. This advancement aims to increase trust and streamline financial verification processes.
Challenges and Outlook
Although the advantages of the creditworthiness document are clear, there are challenges such as protecting personal data and preventing fraud. The proper implementation of regulations and the appropriate use of these documents are essential to overcoming these barriers.
Added Value in the Market
The creditworthiness document offers added value by establishing a framework for the structured assessment of financial capacity, helping tenants and businesses stand out in competitive economic environments.
3. Demonstrating Financial and Economic Solvency
Demonstrating financial solvency is an essential requirement for individuals and legal entities seeking bank financing. Traditional banks focus on gaining a thorough understanding of a customer’s financial situation before granting any loan or credit.
In any case, it’s in your best interest to know what information to submit and how to do so in order to clearly reflect your actual situation and gain access to these financial products.
4. Do You Need to Prove Your Financial Solvency?
This means demonstrating your ability to meet all your outstanding payments, regardless of when they are due.
This implies, therefore, that the following conditions must be met:
Have the necessary resources to pay off all outstanding balances.
Be able to continue doing so over time.
There are three common situations in which you will need to prove this solvency:
Applying for business or personal loans from financial institutions.
Contracts with the government. In many public projects, you must provide guarantees in order to be awarded the contract.
Applying for grants or government assistance.
5. How to Demonstrate Your Financial Solvency?
Regardless of which entity you need to demonstrate this capacity to, it’s essential to know how to do so.
Among the most commonly used documents to prove your financial solvency, we highlight the following:
Statement of total revenue for the past three fiscal years.
Filing of annual financial statements with the Commercial Registry or another official registry. When this is not required, you must submit your certified accounting records.
Proof of professional liability insurance.
A statement of compliance from a financial institution.
Completion of a qualified external audit.
Calculation of net worth or, alternatively, the ratio of assets to liabilities at the close of the most recent fiscal year.
For self-employed individuals and private individuals, submission of the individual income tax return or the value-added tax return.
In certain government calls for proposals, it is also required to demonstrate that the average payment period to suppliers does not exceed the limit set by the tax authorities.
6. Supporting Ratios
We recommend including in your documentation the calculation of certain ratios that will help support your proposal.
In practice, these are usually the same ratios that lenders use to evaluate you.
Therefore, taking the initiative—when the results support your objectives—is highly advisable.
Below, we present the most important ones:
6.1. Financial Solvency or Stability Ratio
The financial solvency or soundness ratio indicates whether receivables cover all outstanding debts.
Ideally, it should range between 1.5 and 2. The higher the ratio, the more idle resources you have; the lower the ratio, the greater the risk of being unable to meet your debt obligations.
We can distinguish between two types, depending on the time horizon analyzed:
– Short-term solvency ratio: Current Assets / Current Liabilities.
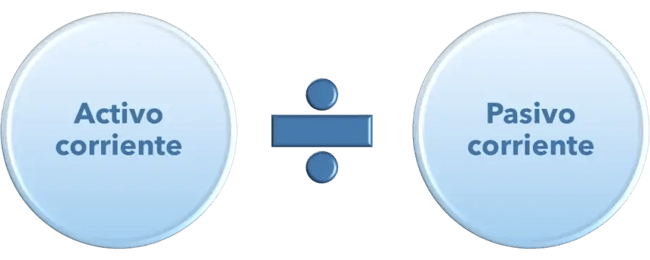
– Long-term solvency ratio: Total Assets / Total Liabilities.
6.2. Debt Ratio
The debt ratio indicates a company’s ability to meet its debt obligations using its own resources.
The lower the ratio, the greater the stability it reflects.
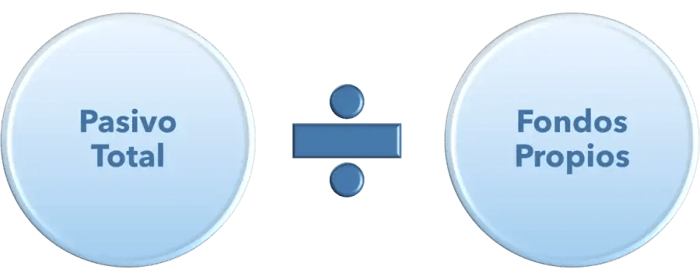
– Debt-to-Equity Ratio: Total Liabilities / Equity.
In addition, the debt classification ratio reveals the liquidity situation by dividing current liabilities due in the short term by total liabilities.
– Debt Classification Ratio: Current Liabilities / Total Liabilities.
5. What can WorkCapital do for you?
Let’s be honest:
Managing this financial data and calculating favorable ratios before applying for business loans or credit requires advanced financial knowledge.
This is especially true when the company’s situation is complex.
In this context, having specialized professionals on your side will allow you to make the best decisions for your business.
At WorkCapital, we offer alternative financing that doesn’t depend on your creditworthiness, since we focus on the party paying back the loans.
This increases your chances of securing financing.
Unlike conventional financing vehicles, such as business loans and credit lines, we offer promissory note discounting and invoice factoring.
So, don’t hesitate:
Contact us with no obligation, and we’ll guide you through the entire process, tailoring our products to your working capital needs.